Picture the first Tuesday morning after you’ve stopped working. Where are you? Who’s with you? What are you looking forward to that afternoon? For many people approaching retirement, those questions are harder to answer than the ones about account balances, yet they may matter just as much.
Many workers haven’t even started on the numbers. According to the U.S. Department of Labor, a 2023 Employee Benefit Research Institute survey suggests that “only 51 percent of workers and/or their spouses have tried to calculate” how much they’ll need to save to live comfortably in retirement.
Before you can know how much is enough, it helps to know what enough looks like for you. That’s where learning how to plan your retirement lifestyle comes in, and it’s the foundation for every financial decision that follows.
What Does Retirement by Design Mean?
Designing your retirement means starting with the life you want and working backward to the numbers. Rather than asking only how much you need, you begin by asking what you’d like your days, relationships, and contributions to look like. Then you evaluate whether your finances can realistically support that picture.
This approach sits at the heart of our MaxAMAZING™ Your Retirement philosophy. Retirement isn’t just about getting by; it’s about living with intention.
Start by Defining Your Retirement Vision
Your retirement vision is a description of the life you hope to live, and it helps to break it into three connected ideas. Quality of life is your overall sense of well-being and fulfillment. Lifestyle is the rhythm of your days, including your activities, relationships, and how you spend your time. Standard of living is the level of spending needed to support that lifestyle.
It’s easy to assume more money automatically leads to a better life, but wealth mainly shapes your standard of living. Lasting fulfillment tends to come from purpose, connection, and living in line with your values. That’s why it can help to work in reverse: define what a fulfilling retirement looks like, decide which routines and relationships support it, and then determine what it will cost. For a closer look at how these three ideas connect, read Living with Intention: Understanding Standard of Living, Lifestyle, and Quality of Life.
Where Do You Want to Live?
Staying in your current home, downsizing, moving closer to grandchildren, or splitting time between two locations can each lead to very different costs. Property taxes, maintenance, insurance, and proximity to healthcare and loved ones all belong in this conversation.
How Do You Want to Spend Your Time?
Think beyond the big trips and imagine an ordinary week. Will you volunteer, consult part-time, take classes, garden, or start a business? Your routine often shapes your budget more than occasional splurges do.
Which Relationships, Experiences, and Causes Matter Most?
Family, friendships, faith communities, and charitable causes often become even more central in retirement. Naming them now can help you plan for travel to see loved ones, support for family members, and the legacy you’d like to leave.
How to Plan Your Retirement Lifestyle
Once your vision feels clearer, it’s time to look at your financial foundation. That includes your assets, debts, cash reserves, insurance coverage, anticipated expenses, and potential income sources.
Social Security is a key piece for most households. The Social Security Administration explains that with a personal online account, “you can get an estimate of your future retirement benefits.” That estimate can be a helpful starting point when deciding when to claim.
Separate Essential Expenses from Lifestyle Goals
Essential expenses include housing, food, utilities, insurance, healthcare, and taxes. Lifestyle goals might include travel, hobbies, gifting, or a vacation property. Many people aim to cover essentials with more predictable income sources while funding lifestyle goals with assets that can adjust as circumstances change.
Consider How Your Spending May Change over Time
Spending in retirement rarely stays flat. The early years may be more active, with travel and new pursuits. Later years may bring lower discretionary spending but potentially higher healthcare costs. Planning for these shifts may help your plan stay realistic.
Discuss Expectations with Your Spouse or Partner
Couples don’t always share the same picture of retirement. One partner may dream of traveling while the other wants to stay close to family, or one may be ready to stop working years before the other. It helps to talk through when and how each of you wants to retire, what an ordinary week together might look like, and how you’d handle health changes or other surprises. We walk through each of these topics in 3 Conversations Every Couple Should Have Before Retiring Together.
Turn Your Lifestyle Goals into Financial Priorities
With your vision and foundation in place, rank your goals by importance and attach estimated costs and timelines to each one. This step turns wishes into priorities you can plan around.
Be sure to include legacy goals as well, such as helping family members or supporting causes you care about. These wishes can influence how much you spend during retirement, how you invest, and how you structure your estate plan.
If you’re not sure where you stand, our Retirement Preparedness Assessment can help you identify strengths and gaps before you make major decisions.
Build Flexible Retirement Income Strategies
Most retirees draw income from several sources, such as Social Security, pensions, portfolio withdrawals, part-time work, and in some cases annuities. Each comes with trade-offs. Annuities, for example, may offer steady income, but they can involve fees, surrender charges, and reduced access to your money.
Timing matters, too. Sequence of returns risk is the possibility that a market downturn early in retirement, just as you begin making withdrawals, could have a lasting effect on how long your savings last. It’s a bit like selling your house during a housing slump; you lock in a lower value and don’t get the chance to benefit if prices recover. A flexible withdrawal approach may help you adjust your spending when markets are volatile.
Align Retirement Investment Strategies with Your Goals
Your portfolio should reflect when you’ll need your money and how much fluctuation you can tolerate. Money you plan to use in the next few years may call for more stable investments, while money you won’t need for a decade or more may have more room to pursue growth. Keep in mind that growth-oriented investments also carry greater market volatility, including the possibility of loss. Diversification may help manage risk, though it doesn’t ensure a profit or protect against losses.
Plan for Taxes, Healthcare, Inflation, and the Unexpected
Taxes: The order in which you draw from taxable, tax-deferred, and tax-free accounts can affect how much you keep over time. Tax laws also change, so decisions made today should be revisited.
Healthcare: Medical costs, insurance premiums, and potential long-term care needs can be significant, especially if you retire before becoming eligible for Medicare.
Inflation: Rising prices can reduce purchasing power over a long retirement, which is one reason many plans include some exposure to growth, balanced against the risks that come with it.
The Unexpected: An emergency reserve and appropriate insurance coverage may help you handle surprises without derailing your long-term goals.
Finding Purpose in Retirement beyond the Numbers
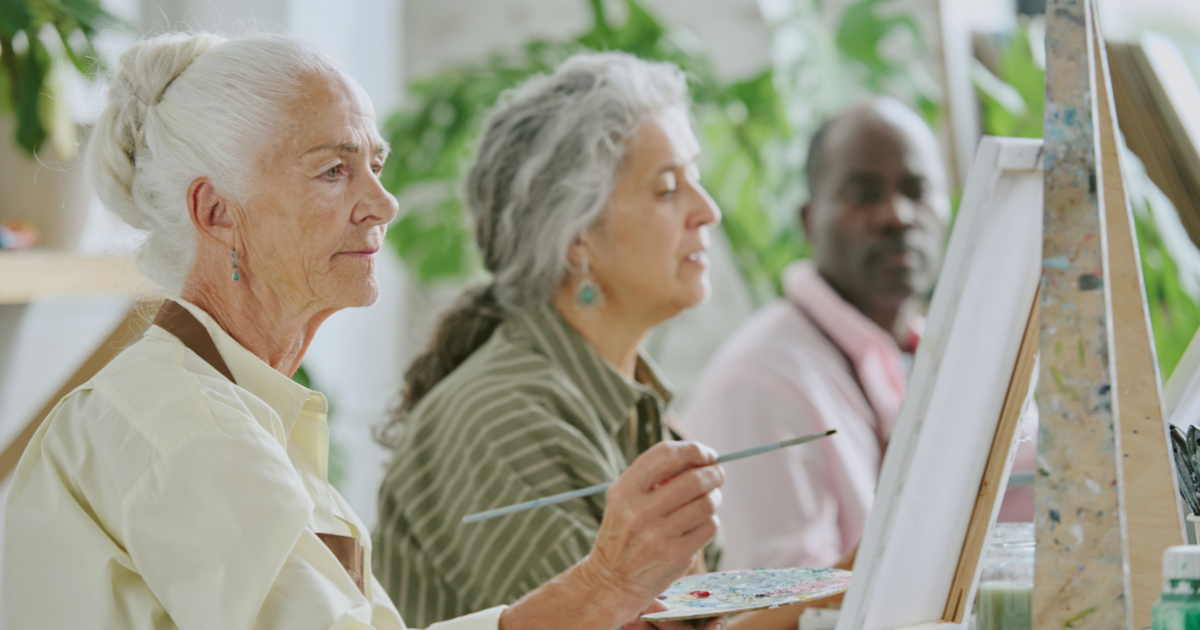
A happy retirement often depends on more than money. Leaving a career can bring a loss of structure and identity, and it’s worth planning for that shift as carefully as you plan your finances.
The National Institute on Aging notes that “people who engage in meaningful, productive activities they enjoy with others feel a sense of purpose.” Volunteering, mentoring, caring for grandchildren, joining community groups, and learning something new are all ways to stay connected. Building these activities into your budget helps ensure purpose isn’t an afterthought.
Not sure where to start? Listen to Norman Calvo: Designing an Adventurous Third Act of Life on the MaxAMAZING™ Your Retirement Podcast. The episode explores how revisiting interests you set aside years ago, and taking small steps toward them, can help you step into retirement as a new beginning rather than a slowdown.
Review Your Retirement Plan as Life Changes
No plan stays perfect for long, and that’s okay. Markets shift, laws change, health evolves, and family circumstances bring new priorities. Reviewing your plan at least once a year, and after major life events, may help keep your finances aligned with the life you actually want to live.
Key Takeaways
- A clear retirement vision built around your values, relationships, and daily routines can give your financial plan direction.
- Separating essential expenses from lifestyle goals may help you decide which priorities need reliable income and which can flex.
- Flexible retirement income strategies and retirement investment strategies should reflect your timeline and your comfort with risk.
- Taxes, healthcare, inflation, and longevity can all affect outcomes, so they deserve a place in your plan from the start.
- Retirement preparedness is an ongoing process, not a one-time event.
Designing Your Retirement Around What Matters Most
Learning how to plan for retirement starts with knowing what you’re planning for. When your financial decisions reflect your values, relationships, and sense of purpose, your plan becomes a tool for living well rather than simply a number to reach.
If you’re ready to connect your vision to a coordinated strategy, request a free consultation with our retirement planning team. We’ll help you build a plan designed around the life you want.